Table of Contents (10 Sections)↓
1. The Commercial Reality of Post-Dated Cheques in Sri Lanka
In Sri Lanka's business landscape, granting credit without security is risky, while formal bank letters of credit (LCs) are too cumbersome for domestic trade. Consequently, the Post-Dated Cheque has become the de facto standard for commercial credit terms.
When a customer hands over a PDC dated 60 days in the future, it provides psychological assurance and a formal negotiable instrument. However, from an accounting perspective, a PDC is not cash—it is merely a conditional promise to pay on a future maturity date.
Recording a PDC prematurely as a direct bank deposit distorts your financial position, misleads management on available liquidity, and causes unintended overdraft charges.
2. Legal Framework of Cheques in Sri Lanka
Cheques in Sri Lanka are governed by the Bills of Exchange Ordinance No. 25 of 1927 (as amended):
3. Operational Hazards of Manual & Spreadsheet PDC Tracking
Relying on manual spreadsheets and physical lockboxes to track hundreds of maturing cheques introduces critical failure points:
4. Double-Entry Accounting Treatment for Incoming Customer PDCs
To maintain pristine ledger accuracy, finance teams must utilize an intermediate current asset account named PDC In-Hand Clearing:
This reflects that the customer's open invoice is provisionally settled by cheque, while keeping the actual Bank cash book strictly aligned with cleared funds.
5. Double-Entry Accounting Treatment for Outgoing Supplier PDCs
Similarly, when your business issues post-dated cheques to suppliers, you must avoid prematurely reducing your bank book balance:
This prevents false bank overdraft calculations while acknowledging that trade liabilities have been settled with a negotiable instrument.
6. Managing Dishonoured & Bounced Cheques
When a deposited cheque bounces (due to 'Insufficient Funds', 'Account Closed', or 'Payment Stopped by Drawer'):
1. Reverse Provisional Settlement: The original customer invoice must be immediately reinstated in Accounts Receivable.
2. Record Bank Dishonour Charges: Banks in Sri Lanka charge a return fee (typically LKR 500 – LKR 1,500) per dishonoured cheque. This fee is debited to Bank Charges (or charged back to the debtor).
3. Double-Entry Journal Entry:
Debit: Accounts Receivable – Customer Account (Gross + Dishonour Fee)
Credit: Bank Current Account (Bank return charge)
Credit: PDC In-Hand Clearing (Reversal of cheque)
4. Credit Hold: The customer's credit limit must be automatically locked to prevent further dispatches until the dishonoured amount is recovered.
7. Presentation Windows, Banking Deadlines & LankaClear Cycles
In Sri Lanka, physical cheque clearing is handled electronically via the LankaPay / LankaClear Cheque Imaging and Truncation (CIT) System:
8. Cashflow Forecasting with Maturing PDC Schedules
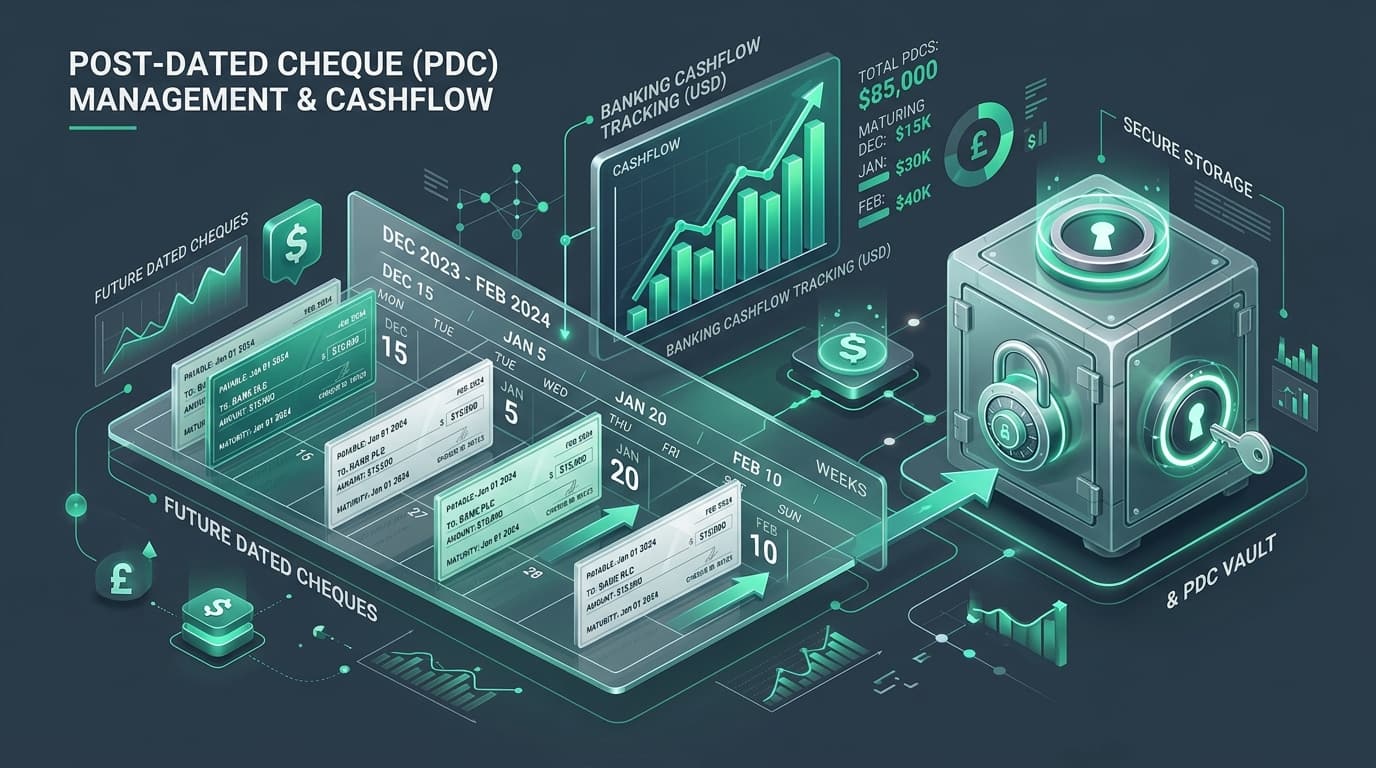
Because PDCs contain fixed future dates and verified amounts, they offer valuable predictability for working capital management:
9. Automated PDC Registry in SyncBooks
SyncBooks features a dedicated Post-Dated Cheque Management workspace built specifically for Sri Lankan business workflows:
Explore SyncBooks's Banking & Cheque workspace to automate PDC registers, maturity reminders, and dishonour workflows.
10. Frequently Asked Questions
Can a business deposit a post-dated cheque before its maturity date?
No. If a cheque is deposited prior to its face date, the drawee bank will reject the cheque with the return reason 'Post-Dated Cheque'. Cheques can only be presented on or after their written date.
How long is a cheque valid in Sri Lanka before becoming stale?
Under Sri Lankan banking practice, a cheque is valid for 6 months from the date written on the face of the cheque. After 6 months, it becomes 'stale' and cannot be cleared without re-validation by the drawer.
Why shouldn't I record an incoming PDC directly to my bank ledger?
Recording a PDC directly in your bank account falsely inflates your cash balance before the funds have actually cleared, leading to inaccurate financial reports and potential bounced supplier cheques.
What legal action can be taken if a customer's cheque bounces in Sri Lanka?
Under the Debt Recovery (Special Provisions) Act No. 2 of 1990 and summary procedure provisions of the Civil Procedure Code, a dishonoured cheque allows the creditor to obtain an expedited decree nisi against the debtor.
How does a PDC Clearing Account work in double-entry bookkeeping?
The PDC Clearing Account acts as an intermediate holding ledger (Current Asset for receipts, Current Liability for payments). It temporarily reflects the settlement of trade balances while keeping the actual Bank cash book strictly aligned with bank statements.
How does SyncBooks help manage post-dated cheques?
SyncBooks provides a central electronic PDC vault that tracks maturity dates, sends automated banking alerts, generates double-entry clearance journals on maturity, and handles cheque bounce reversals with a single click.
📌Key Takeaway & Summary
Post-Dated Cheques remain vital to Sri Lankan commercial liquidity, but managing them manually exposes businesses to dishonour risks and cash flow blindspots. By applying rigorous double-entry clearing accounts and automating maturity schedules with SyncBooks, finance teams gain absolute control over their cash pipeline.
Published by the SyncBooks Knowledge & Research Team — Sri Lanka Accounting Cloud.